Step 01
Repair the profile
We clear the blockers on personal and business credit before a bank's algorithm finds them. Production on the book does not fix a mismatch, a stale inquiry, or a bureau the next bank will pull.
National Brokers Group · Partnership with Stacking Capital Miami, Sept 29–30
You write a book. That book is not a capital stack. NBG brought Stacking in so you can access funding without leaving the room. One advisor, live on Zoom. You stay with NBG. We run the work.
Book a Bankable Blueprint Call →500+ owners funded · $90M+ secured · $100K minimum, in writing
The engagement · NBG partnership
You need funding, not a motivational talk. You write a book. That book is not a capital stack. NBG brought Stacking in. We run the work. You stay with NBG. Institutions decide approvals, limits, and terms.
Four steps
If you write insurance or run an agency, production is one machine. Capital is another. These four steps are how we build the second one, with you on the Zoom, not after you hang up.
Step 01
We clear the blockers on personal and business credit before a bank's algorithm finds them. Production on the book does not fix a mismatch, a stale inquiry, or a bureau the next bank will pull.
Step 02
Lender compliance, utilization, and the banking relationships a tier-one bank wants to see. We do this while you keep writing cases. The stack waits until it can hold weight.
Step 03
Live on Zoom with your advisor. The right banks, in the right order, at the right spacing. You are on the call. We do the work. This is not nine tabs at midnight after a lock-in high.
Step 04
Round two: term, lines, SBA. The 0% window is a step, not a cliff. That later round is why the lock-in afternoon covers 3 / 5 / 7 year exits.
Two ways this goes
You can leave Miami and apply at every shop that handed you a flyer. Or you can stay with NBG and let us sequence the same institutions, live, with an exit written first.
Without an advisor
With Stacking Capital
 ChaseApproved
 American ExpressApproved
 Bank of AmericaIn review
 U.S. BankSequenced next
The machine · four phases
This is the work we run after you book. You stay with NBG. We stay on Zoom with you. The 3 / 5 / 7 year exit is not a slide at the end. It is why phase four exists, and why it gets said in the room on September 30.
Phase one · weeks 1–6 · Preparation
You come on. We start with your profile, personal and business, before anyone applies. The Bankable Scan runs the points a bank's algorithm will run. Compliance items get named and fixed. Checking relationships at tier-one banks get opened and seasoned. Your book keeps moving. The stack waits, because sending applications early is the one mistake you cannot undo.
Phase two · the rounds · Sequenced applications
Then the applications start, with you on the call, one advisor, the banks ordered by who they pull and how many inquiries they will tolerate. Between rounds we remove hard pulls that never became accounts and let the new limits season. Speed is not the goal. When your situation can move fast, we do not slow it down. When it cannot, we do not pretend.
Phase three · in parallel · Business credit
While the card rounds run, we build the business itself: tradelines reporting, scores climbing, a bank rating the institutions can underwrite on its own. An agency that only ever lives on your personal credit is one underwriting conversation away from a wall. This phase is how you stop being that agency.
Phase four · graduation · the 0% exit
When the 0% interest period runs out, the exit you wrote in week one executes. Balances move. Term, lines, SBA come into range on the business you spent six months building. Cards were the door. This is the building. That is the 3-year, 5-year, and 7-year conversation on the lock-in stage. Not a slogan. A path.
The products
Four products. Each one enters at a different point. Which of them you can carry is decided by the institution and by your situation, never by this page, and never by the stage.
Opening rounds
Working capital you can put on the next marketing push, the next hire, or the next block of leads, without taking a point from the book to a cash-advance shop.
Revolving
A line the agency can draw, repay, and draw again when persistency, recruiting, or a down month asks for cash you do not want to pull from commissions.
Fixed
One lump on a schedule the business can plan around, the kind of debt you can put next to a 3 / 5 / 7 year exit without hoping a promo date saves you.
Graduation
Long duration at prime-range rates, underwritten on the business we built in parallel. This is the later round. This is why the first six months are quiet on purpose.
Stacks that already exist
Individual outcomes. Institutions decided every number. Not a promise for you, proof the work has a shape. These are the public Blueprint figures. We did not invent a dollar for this page.
Andrew came in as an established owner with a profile that could support real limits. It had just never been prepared or sequenced. Compliance first. Banks ordered by bureau sensitivity. Applications live on Zoom. Under four months later, his stack crossed five hundred twenty-four thousand five hundred dollars.
“They got me over half a million in total funding. Started with 0% cards, then layered in loans and lines of credit. Two rounds, eight products, all strategic.”
$524,500CHASE · 0%
Nine approvals is not nine lucky applications. It is one prepared profile meeting nine banks in the order each one wanted to see it. The first forty-eight hours produced eighty thousand because the first banks in Brandy's sequence were chosen for exactly that reason.
“I don’t think I would have had the connections, the relationships, and the organization to get to where I am without you guys.”
$222,000AMEX · 9 APPROVALS
Frank is the whole arc in one client. Card rounds built the base. Business credit ran in parallel. A later round graduated him: a three hundred fifty thousand dollar SBA loan. That loan is what the first six months were quietly preparing for, the same later-round conversation the lock-in covers.
 $350,000SBA LATER ROUND

Public Blueprint figure. Real estate investor, Hartford. He stayed in the process when the limits started landing. That is the whole point of a sequence: you do not improvise after the first yes.
“Everything you said you would do actually worked like a charm. I was surprised when we got some high limits. You just got to trust the process.”
Public Blueprint figure. Healthcare professional, Florida. Two companies said no before the stack landed. The ticker on the Blueprint page still says that sentence for a reason.
“Having lines of credit and funding help not only me but every business to expand. That is very useful.”

In writing
If you qualify and you complete the program, you access at least $100,000. That number is written into the agreement before you pay us a dollar. Ask the last shop that pitched you in a hallway if they will sign that. Their model will not let them. Ours is built on it.
Ask them, on the record, if $100,000 is in the contract.
If they blink, you already have the answer. This is not another hallway pitch.
Inside the engagement
Not a portal login and a hope. One advisor. The scan. The cleanup. The banks. Your spouse or partner on the same engagement if you want them there.
Questions you will ask anyway
You came for capital. These are the questions brokers and agency owners actually ask. Institutions still decide. We still do the work.
A one-time flat fee for six to twelve months of the program. No backend percentage. A broker gets richer every time you borrow more. We built the opposite incentive: the more capital you access, the cheaper every dollar of the fee becomes. We will tell you the number on the Blueprint call. We will not hide a success fee in the fine print after you leave Miami.
It depends on your situation. Some stacks move in days once the profile is ready. Brandy had $80,000 in the first 48 hours; another public Blueprint client, Erwin, had $45,000 in seven days. Most owners from a room like this spend the first weeks on the scan, compliance, and banking. We do not fire applications the night you book just to make the lock-in feel like a win. Sending them early is the mistake you cannot undo.
No. We are not a credit-repair subscription. We do not spend a year arguing with bureaus while your production waits. We repair what a bank will ding: mismatches, utilization, inquiries that never became accounts, compliance items. Then we apply in sequence. Stacking Capital is a capital advisory. Not a lender. Not a credit-repair company.
A broker's fee grows with every dollar you borrow. They shotgun apps, take ten to twenty percent, and disappear when the 0% window ends. We are one advisor, live on Zoom, flat fee, exit written first. You stay with NBG. We do not become your upline, your agency, or the person who “has your book.” We run the capital work. That does not change.
The exit you wrote in week one fires. Balances move onto term, lines, or SBA if the institution will have you. That is phase four. That is also why the lock-in afternoon covers 3 / 5 / 7 year exits, because a stack with no exit is just a promo date with a calendar invite. We do not leave you staring at 29% APR and a hope.
No. Cards open the door. Lines, term, and SBA are the building. If someone only sells you cards and calls it funding, ask them what happens in month thirteen, and ask them if they will still be on Zoom with you when the agency needs a later round. We will.
Who this is for
If you write insurance or run an agency and you came through NBG, start here.
NBG × Stacking Capital
You came for capital. One advisor, live on Zoom. You stay with NBG. We run the work. NBG Sales Conference & Lock-In, Miami, September 29–30.
Book a Bankable Blueprint Call →If you explore funding for yourself, you should also know you can refer other owners. You stay with NBG. We run the file.
Public proof
The same figures as the Blueprint page. 500+ business owners funded. $90M+ secured. Reviews below are verified Trustpilot reviews already used on join.stacking.capital/blueprint, not invented for Miami.
Verified Trustpilot reviews
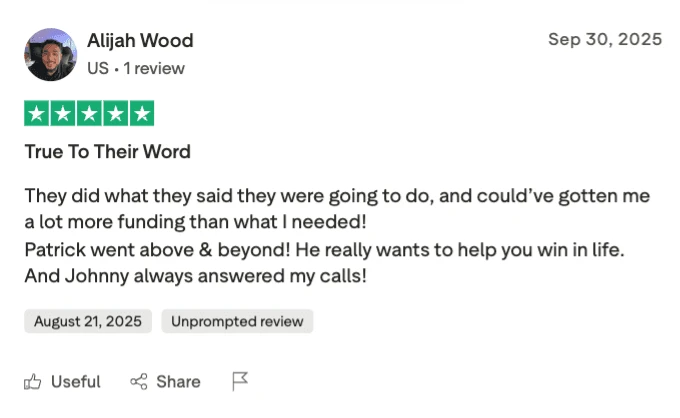
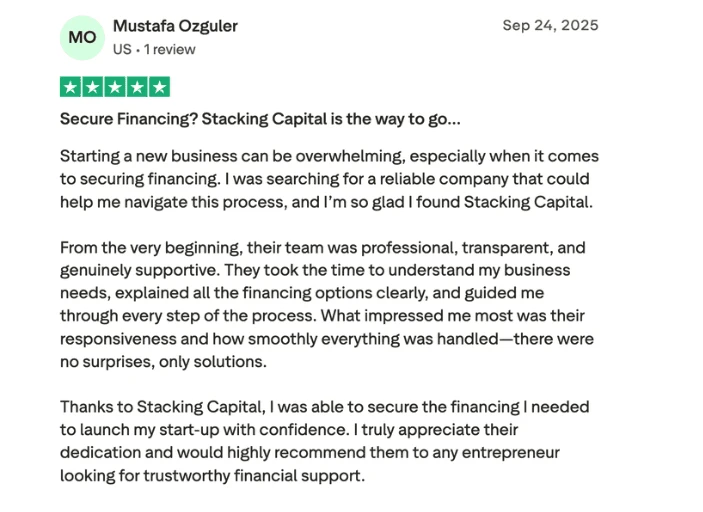
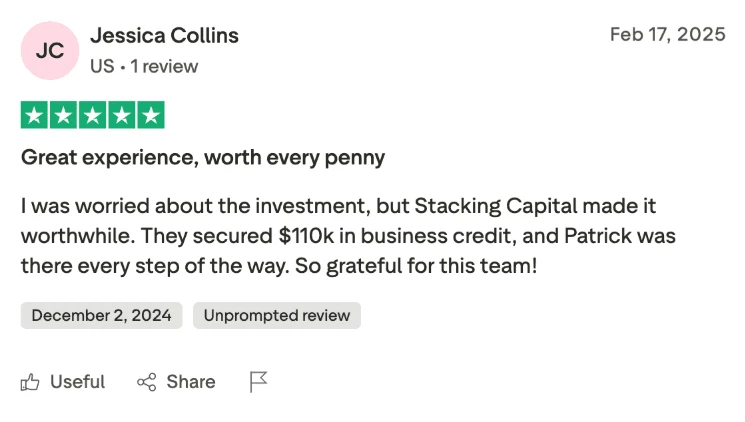
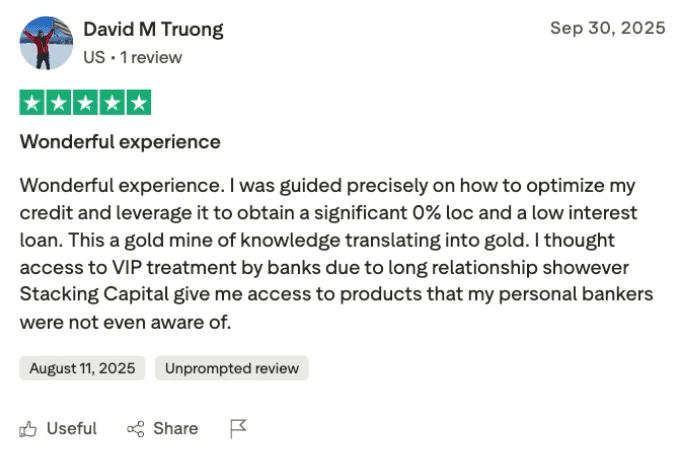
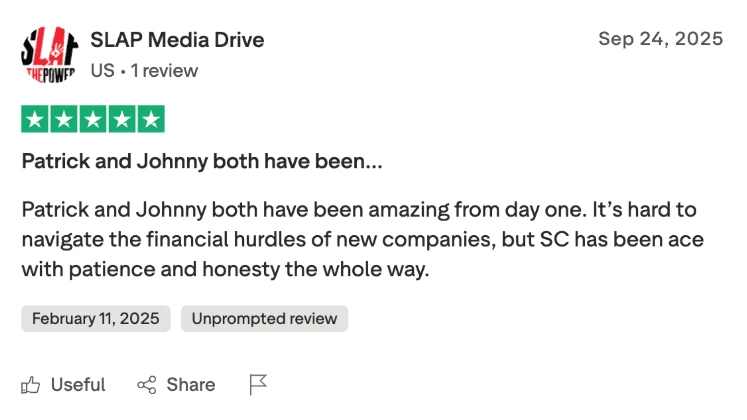
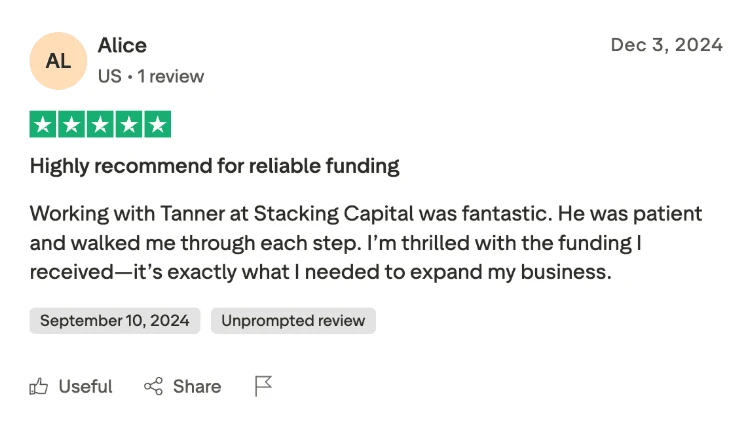
National Brokers Group × Stacking Capital referral partnership page for brokers and agency owners looking for funding. Stacking Capital is not a lender. Institutions decide approvals, limits, terms. No promise on amount, rate, or close date. Andrew, Brandy, Frank, Menard, and Dr. Truong are public Stacking Capital client outcomes from the Blueprint page. Trustpilot images and the 500+ / $90M+ figures are the public Blueprint proof set.
Sept 29–30, 2026 · EB Hotel Miami
4299 NW 36th Street, Miami, FL 33166
Book the Blueprint call
NBG Sales Conference & Lock-In · Miami, Sept 29–30. You stay with NBG.
Book a Bankable Blueprint Call